
Edmonton Mortgage Rates
By Daniel De Sousa · Updated November 3, 2026
Advertised rates can change within 24 hours, and some companies buy down the rates they advertise. So this page uses example rates, 4.75% fixed and 4.25% variable, to show what you’d pay on an Edmonton home. They aren’t quotes or today’s market rates. Prime is 4.70% (RBC). The Bank of Canada raised its policy rate to 2.50% on October 28, and variable rates moved with prime.
We review this page after every Bank of Canada rate decision.
Key Takeaways
– This page’s example rates are 4.75% fixed and 4.25% variable. They show the math and aren’t quotes. Prime is 4.70% (RBC).
– The Bank of Canada raised its policy rate to 2.50% on October 28, its first increase since July 2023. Its next decision is December 9.
– Variable rates follow prime and moved up with the Bank. Fixed rates follow bond yields and lender margins, and the five-year Government of Canada bond yield eased to 3.51% on October 30.
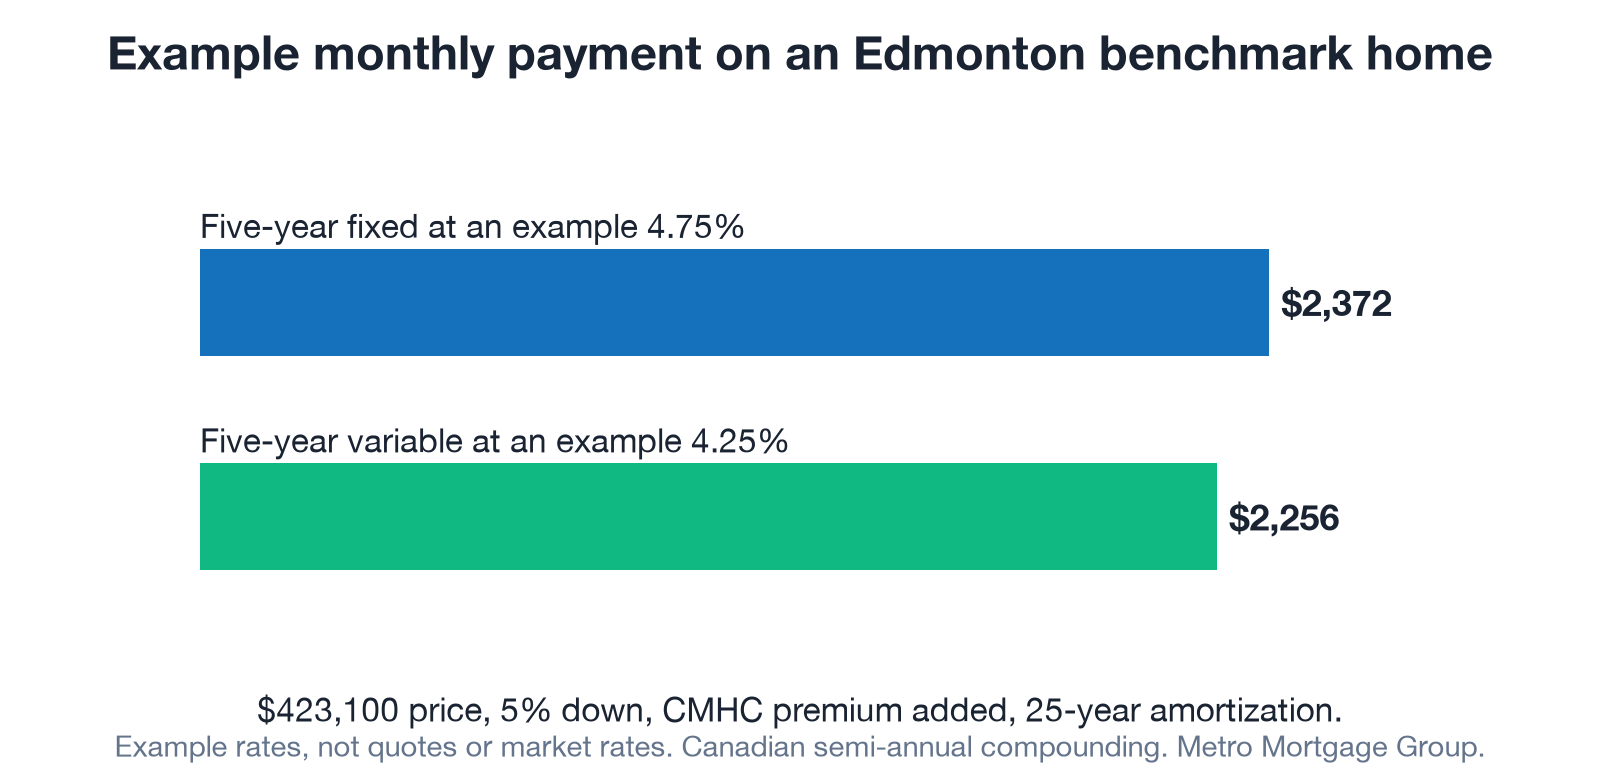
– On the Greater Edmonton Area’s September benchmark home ($423,100) with 5% down, the example fixed payment is about $2,372 a month and the example variable payment about $2,256.
– Greater Edmonton Area sales fell 10.3% year over year in September while new listings rose 11.3%, so buyers have more choice this fall.
Why doesn’t this page list today’s Edmonton mortgage rates?
Because a published rate can be out of date by the next day. Advertised rates can change within 24 hours, and some companies buy down the rates they advertise, so a low number online may not be one you can get. We use example rates for the math and give you a real quote on your file. Insured rates apply when you put down less than 20%, and they’re usually the lowest rates available because the mortgage is backed by default insurance.
| Product | Rate |
|---|---|
| Example five-year fixed | 4.75% |
| Example five-year variable | 4.25% |
| Prime rate | 4.70% |
| Bank of Canada policy rate | 2.50% |
Advertised rates assume a strong credit score, stable income and a standard property. Your quote can differ for a rental, a self-employed income, a larger loan or a longer amortization. Our Alberta mortgage rates page covers the same products province-wide.
Why did mortgage rates go up after the Bank of Canada’s October decision?
The Bank of Canada raised its policy rate by 25 basis points to 2.50% on October 28, 2026 (Bank of Canada). It said CPI inflation has been around 3% since April and is expected to rise to about 3½% by the end of the year, mainly because oil prices have stayed high. Our recap of the decision covers what it means for your mortgage.
Variable rates follow lender prime, which moves with the Bank’s policy rate. The big banks raised prime from 4.45% to 4.70% effective October 29 (RBC, National Bank), and variable mortgage rates tied to prime moved with it.
Fixed rates follow the five-year Government of Canada bond yield, plus a margin each lender sets. That yield was 3.51% on October 30, down from 3.68% on September 28 (Bank of Canada). An easing yield does not always mean a lower fixed rate right away, because lenders set their own margins.
The Bank said “there could be a need to increase the policy rate further” and that it will proceed carefully. It also expects new US tariffs to slow growth in the fourth quarter before growth picks up in 2027 (Bank of Canada). Our five-year fixed rate guide explains the bond yield link in more detail.
What would an Edmonton home cost each month at example rates?
The Greater Edmonton Area benchmark home price was $423,100 in September 2026, according to the REALTORS Association of Edmonton. Here’s what that home costs each month with the minimum 5% down payment:
| Amount | |
|---|---|
| Purchase price (Greater Edmonton Area benchmark, September) | $423,100 |
| Minimum down payment (5%) | $21,155 |
| Mortgage before insurance | $401,945 |
| CMHC insurance premium (4.00%) | $16,078 |
| Total insured mortgage | $418,023 |
The 5% minimum applies to homes up to $500,000 (Financial Consumer Agency of Canada), and CMHC charges a 4.00% premium when the loan is above 90% of the price (CMHC).
| Option | Rate | Monthly payment (25-year amortization) |
|---|---|---|
| Five-year fixed | 4.75% | about $2,372 |
| Five-year variable | 4.25% | about $2,256 |
Payments use Canadian semi-annual compounding and exclude property tax and heating.
Variable starts about $116 a month lower in this example. The variable rate would have to rise by 50 basis points, two quarter-point increases, before its payment reached the fixed payment. Whether that cushion is worth the uncertainty depends on your budget. Our fixed versus variable comparison walks through the trade-offs, and our affordability guide shows what you’d qualify for.
How is Edmonton’s housing market affecting borrowers?
The REALTORS Association of Edmonton reported 1,959 sales across the Greater Edmonton Area in September 2026, down 8.8% from August and 10.3% from September 2025 (REALTORS Association of Edmonton). New listings rose 11.3% year over year to 3,864. The average selling price was $466,080, up 2.9% from a year earlier, while the benchmark price of $423,100 was down 0.3%.
The association’s board chair said typical seasonal trends suggest sales will not rebound until after year end. Inventory was 16.7% higher than a year earlier.
For buyers, a slower market with more listings means more choice and more time to negotiate. It also means a rate hold matters. If you take four to eight weeks to find the right home, a hold protects you if fixed rates rise while you look. If you’re buying your first home, our first-time home buyer guide covers the programs and costs.
What rate will you actually get?
Your rate depends on several things beyond the market:
- Whether the mortgage is insured. Insured mortgages (less than 20% down) usually get the lowest rates.
- The term. Three-year and five-year terms are priced separately, so either one can be lower at a given time.
- Your credit score, income type and debt levels.
- The property. Rentals, larger multi-unit buildings and some condos can price higher.
- Where you get the mortgage. Banks, monoline lenders that work through brokers, and Alberta credit unions all compete for Edmonton borrowers.
We work with more than 30 lenders, including ATB Financial, Servus Credit Union, CMLS and Scotiabank, so we can compare them on your actual file rather than on advertised rates alone.
Should you lock in a rate now?
If you expect to buy or renew in the next four months, getting a rate hold now costs nothing and protects you if fixed rates rise. When we pre-approve you, we hold a rate with one lender and keep watching the market while you shop. We can usually turn around a pre-approval within 24 hours.
If rates fall before you close, a hold doesn’t lock you out of a lower rate, although how that works varies by lender. Our guides on rate holds and when to lock your rate explain the details. Renewing instead of buying? See our mortgage renewal guide.
Frequently asked questions
What is the best five-year fixed mortgage rate in Edmonton right now?
It changes too often to print here: advertised rates can move within 24 hours, and some companies buy down the rates they advertise. Your own rate depends on your down payment, credit, income and property, so ask for a quote based on your file.
Are Edmonton mortgage rates different from Calgary or the rest of Canada?
It can. Lenders and brokers are licensed and compete province by province, so rates can differ between Edmonton and Toronto, and the same lender may quote differently in different markets. Alberta has its own credit unions and ATB Financial, which compete alongside the national banks and monoline lenders.
Will mortgage rates go down in Edmonton?
That depends on inflation and bond yields. The Bank of Canada just raised its policy rate and expects inflation to reach about 3½% by the end of the year before returning to 2% in the middle of 2028. Variable rates would only fall if prime falls, which normally takes a cut from the Bank. Its next decision is December 9, 2026.
Should I choose fixed or variable in Edmonton right now?
In our example, variable is 50 basis points lower, about $116 a month less on the Greater Edmonton Area benchmark home with 5% down. Choose fixed if you need a predictable payment for five years. Choose variable if your budget can absorb increases and you’d rather start with the lower payment.
How often is this page updated?
We review this page after every Bank of Canada rate decision. The rates shown are examples, not quotes, so call us for a current quote before you make a decision.
Talk to an Edmonton mortgage broker
If you’re buying, renewing or refinancing in the next few months, we’ll compare your options across our 30+ lenders and show you the payments on your actual numbers. Call 780-974-1270, email info@MetroMortgageGroup.ca, or learn more about working with our Edmonton mortgage broker team.
About the author: Daniel De Sousa is co-owner of Metro Mortgage Group and an Edmonton mortgage broker. He works with first-time buyers, renewals and pre-approvals across Alberta.
Sources
- Bank of Canada, Policy interest rate announcement, October 28, 2026, retrieved 2026-11-02, https://www.bankofcanada.ca/2026/10/fad-press-release-2026-10-28/
- Bank of Canada, Canadian bond yields, retrieved 2026-11-02, https://www.bankofcanada.ca/rates/interest-rates/canadian-bonds/
- RBC Royal Bank, RBC Royal Bank announces change to prime rate, October 28, 2026, retrieved 2026-11-02, https://www.newswire.ca/news-releases/rbc-royal-bank-announces-change-to-prime-rate-837555648.html
- REALTORS Association of Edmonton, New inventory is still being added, but sales have slowed for fall, September 2026 statistics, retrieved 2026-11-02, https://realtorsofedmonton.com/statistic/new-inventory-is-still-being-added-but-sales-have-slowed-for-fall/
- CMHC, Mortgage loan insurance premiums, retrieved 2026-09-28, https://www.cmhc-schl.gc.ca/consumers/home-buying/mortgage-loan-insurance-for-consumers/cmhc-mortgage-loan-insurance-cost
- Financial Consumer Agency of Canada, Down payment, retrieved 2026-09-28, https://www.canada.ca/en/financial-consumer-agency/services/mortgages/down-payment.html
Rates shown are examples. They change often; call for a current quote.