
Calgary Mortgage Rates
By Daniel De Sousa · Updated November 3, 2026

Advertised rates can change within 24 hours, and some companies buy down the rates they advertise. So this page uses example rates, 4.75% fixed and 4.25% variable, to show what you’d pay on a Calgary home. They aren’t quotes or today’s market rates. Prime is 4.70% (RBC). The Bank of Canada raised its policy rate to 2.50% on October 28, and variable rates moved with prime.
We update this page every month and after each Bank of Canada rate decision.
Key Takeaways
– This page’s example rates are 4.75% fixed and 4.25% variable. They show the math and aren’t quotes. Prime is 4.70% (RBC).
– The Bank of Canada raised its policy rate to 2.50% on October 28, its first increase since July 2023. Its next decision is December 9.
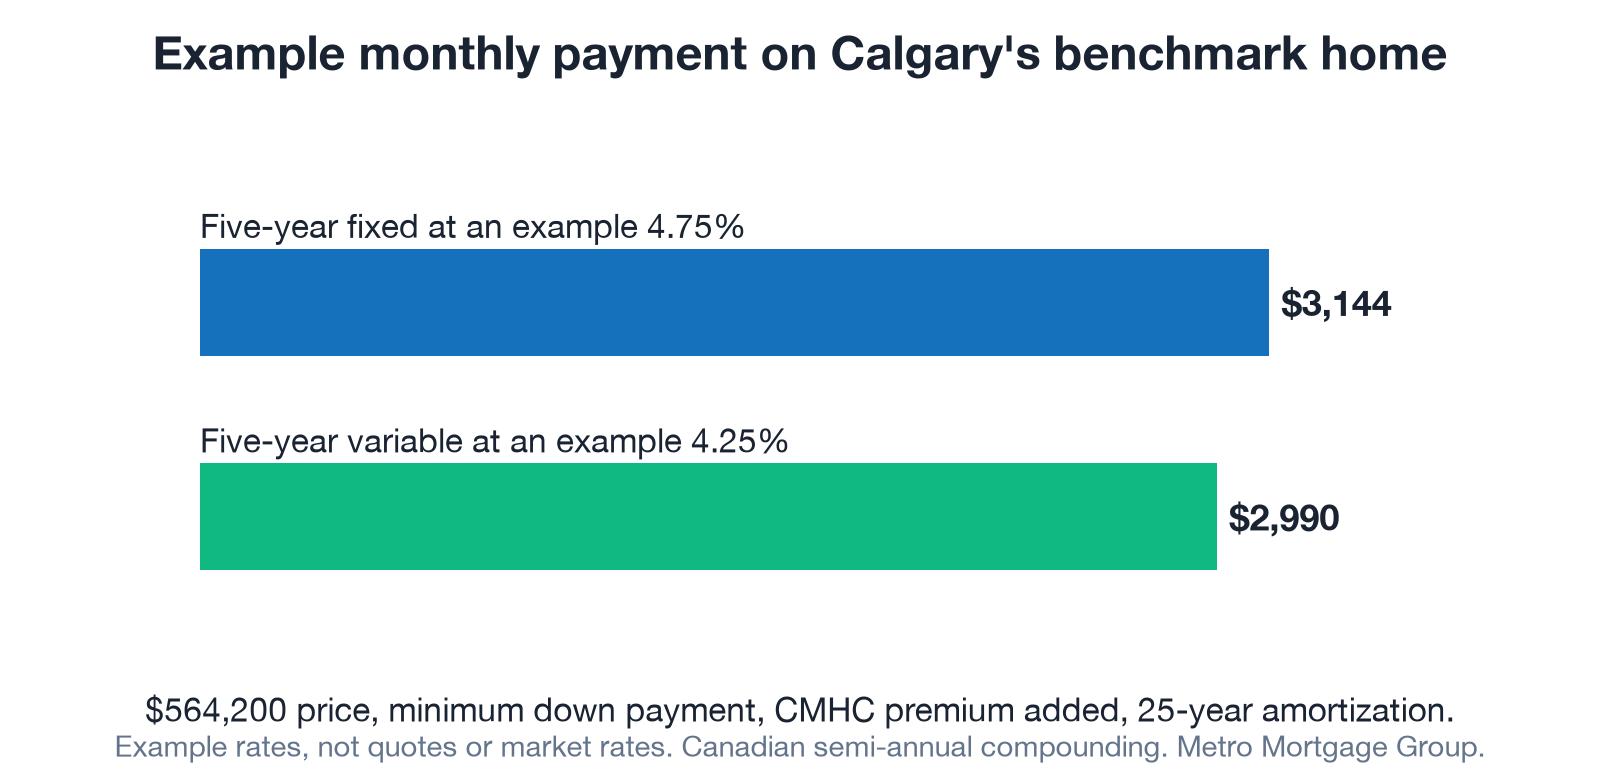
– On Calgary’s October benchmark home ($564,200) with the minimum down payment, the example fixed payment is about $3,144 a month and the example variable payment about $2,990.
– Calgary sales fell 15.3% year over year in October, and there is just under four months of supply on the market (CREB).
Why doesn’t this page list today’s Calgary mortgage rates?
Because a published rate can be out of date by the next day. Advertised rates can change within 24 hours, and some companies buy down the rates they advertise, so a low number online may not be one you can get. We use example rates for the math and give you a real quote on your file. Insured rates apply when you put down less than 20%, and they’re usually the lowest available because default insurance backs the loan.
| Product | Rate |
|---|---|
| Example five-year fixed | 4.75% |
| Example five-year variable | 4.25% |
| Prime rate | 4.70% |
| Bank of Canada policy rate | 2.50% |
Advertised rates assume strong credit, stable income and a standard property. A rental, self-employed income, a larger loan or a longer amortization can change your quote. Our Alberta mortgage rates page covers the same products province-wide, and our Edmonton mortgage rates page does the same for the capital region.
Why did mortgage rates go up after the Bank of Canada’s October decision?
The Bank of Canada raised its policy rate by 25 basis points to 2.50% on October 28, 2026 (Bank of Canada). It said CPI inflation has been around 3% since April and is expected to rise to about 3½% by the end of the year, mainly because oil prices have stayed high. Our recap of the decision covers what it means for your mortgage.
Variable rates follow lender prime, which moves with the Bank’s policy rate. The big banks raised prime from 4.45% to 4.70% effective October 29 (RBC, National Bank), and variable mortgage rates tied to prime moved with it.
Fixed rates follow the five-year Government of Canada bond yield, plus a margin each lender sets. That yield was 3.51% on October 30, down from 3.68% on September 28 (Bank of Canada). An easing yield does not always mean a lower fixed rate right away, because lenders set their own margins. The Bank said “there could be a need to increase the policy rate further” and that it will proceed carefully (Bank of Canada). Our five-year fixed rate guide explains the bond yield link in more detail.
What would a Calgary home cost each month at example rates?
The City of Calgary’s total residential benchmark price was $564,200 in October 2026, down 0.4% from a year earlier (CREB). Because that price is above $500,000, the minimum down payment is 5% of the first $500,000 plus 10% of the portion above it (Financial Consumer Agency of Canada).
| Amount | |
|---|---|
| Purchase price (City of Calgary benchmark, October) | $564,200 |
| Minimum down payment (5% of $500,000 + 10% of $64,200) | $31,420 |
| Mortgage before insurance | $532,780 |
| CMHC insurance premium (4.00%) | $21,311 |
| Total insured mortgage | $554,091 |
The loan works out to about 94% of the price, which puts it in CMHC’s 4.00% premium band (CMHC).
| Option | Rate | Monthly payment (25-year amortization) |
|---|---|---|
| Five-year fixed | 4.75% | about $3,144 |
| Five-year variable | 4.25% | about $2,990 |
Payments use Canadian semi-annual compounding and exclude property tax and utilities.
Variable starts about $154 a month lower in this example. Its rate would have to rise by 50 basis points, two quarter-point increases, before the variable payment matched the fixed payment. Whether that cushion is worth the uncertainty comes down to your budget. Our fixed versus variable comparison walks through it.
Calgary’s October benchmark is about $141,100 higher than the Greater Edmonton Area’s September benchmark of $423,100 (REALTORS Association of Edmonton), the latest figure for each board. At the same example rate, that difference adds roughly $772 a month to a fixed payment.
How is Calgary’s housing market affecting borrowers?
CREB reported 1,592 sales in the City of Calgary in October 2026, down 15.3% from a year earlier, while new listings fell 9.4% to 2,928 (CREB). Inventory stood at 6,173 homes, just under four months of supply, and the benchmark price eased from September.
CREB’s chief economist, Ann-Marie Lurie, said supply choice in the new, rental and resale markets has taken much of the pressure off prices this year, with much of the downward pressure in the oversupplied higher-density segments.
With more homes on the market and fewer buyers, you have time to compare properties and negotiate. That time also makes a rate hold worth having, since rates can move before you’re ready to buy. If you’re buying your first home, our first-time home buyer guide covers the programs and costs.
What rate will you actually get?
Your rate depends on more than the market:
- Whether the mortgage is insured. Insured mortgages (less than 20% down) usually get the lowest rates.
- The term. Three-year and five-year terms are priced separately, so either one can be lower at a given time.
- Your credit score, income type and existing debts.
- The property. Rentals, larger multi-unit buildings and some condos can price higher.
- The lender. Banks, monoline lenders that work through brokers, and Alberta credit unions all lend in Calgary.
We work with more than 30 lenders, including ATB Financial, Servus Credit Union, CMLS and Scotiabank, so we compare them on your actual file rather than on advertised rates alone.
Should you lock in a rate now?
If you plan to buy or renew within the next four months, a rate hold costs nothing and protects you if fixed rates rise. Lenders typically hold a preapproved rate for 60 to 130 days, depending on the lender (Financial Consumer Agency of Canada). When we pre-approve you, we hold a rate with one lender and keep watching the market while you shop, and we can usually turn a pre-approval around within 24 hours.
Our guides on rate holds and when to lock your rate cover the details. If your mortgage is coming up for renewal instead, start with our mortgage renewal guide.
Frequently asked questions
What is the best five-year fixed mortgage rate in Calgary right now?
It changes too often to print here: advertised rates can move within 24 hours, and some companies buy down the rates they advertise. Your own rate depends on your down payment, credit, income and property, so ask for a quote based on your file.
Are Calgary mortgage rates different from Edmonton’s?
Rates can differ by market, though Calgary and Edmonton sit in the same province. The difference is house prices: Calgary’s October benchmark was about $141,100 higher than the Greater Edmonton Area’s September benchmark, which means a larger mortgage and a higher down payment on a typical home.
How much do I need for a down payment on a Calgary home?
On a home priced between $500,000 and $1.5 million, the minimum is 5% of the first $500,000 plus 10% of the rest. On Calgary’s October benchmark of $564,200, that’s $31,420. Homes of $1.5 million or more need 20% down.
Will mortgage rates in Calgary go down?
That depends on inflation and bond yields. The Bank of Canada just raised its policy rate and expects inflation to reach about 3½% by the end of the year before returning to 2% in the middle of 2028. Variable rates fall only if prime falls, which normally takes a cut from the Bank. Its next decision is December 9, 2026.
Should I choose fixed or variable in Calgary right now?
In our example, variable is 50 basis points lower, about $154 a month less on Calgary’s benchmark home with the minimum down payment. Choose fixed if you need a predictable payment for the full term. Choose variable if your budget can absorb increases and you’d rather start lower.
Talk to a Calgary mortgage broker
If you’re buying, renewing or refinancing in Calgary in the next few months, we’ll compare your options across our 30+ lenders and show you the payments on your own numbers. Call 780-974-1270, email info@MetroMortgageGroup.ca, or learn more about working with our Calgary mortgage broker team.
About the author: Daniel De Sousa is co-owner of Metro Mortgage Group and an Edmonton mortgage broker. He works with first-time buyers, renewals and pre-approvals across Alberta.
Sources
- Bank of Canada, Policy interest rate announcement, October 28, 2026, retrieved 2026-11-02, https://www.bankofcanada.ca/2026/10/fad-press-release-2026-10-28/
- Bank of Canada, Canadian bond yields, retrieved 2026-11-02, https://www.bankofcanada.ca/rates/interest-rates/canadian-bonds/
- RBC Royal Bank, RBC Royal Bank announces change to prime rate, October 28, 2026, retrieved 2026-11-02, https://www.newswire.ca/news-releases/rbc-royal-bank-announces-change-to-prime-rate-837555648.html
- CREB, City of Calgary Monthly Statistics, October 2026, retrieved 2026-11-02, https://www.creb.com/Housing_Statistics/documents/10_2026_Calgary_Monthly_Stats_Package.pdf
- REALTORS Association of Edmonton, New inventory is still being added, but sales have slowed for fall, September 2026 statistics, retrieved 2026-11-02, https://realtorsofedmonton.com/statistic/new-inventory-is-still-being-added-but-sales-have-slowed-for-fall/
- CMHC, Mortgage loan insurance premiums, retrieved 2026-09-28, https://www.cmhc-schl.gc.ca/consumers/home-buying/mortgage-loan-insurance-for-consumers/cmhc-mortgage-loan-insurance-cost
- Financial Consumer Agency of Canada, Down payment and Getting preapproved for a mortgage, retrieved 2026-09-28, https://www.canada.ca/en/financial-consumer-agency/services/mortgages/down-payment.html
Rates shown are examples. They change often; call for a current quote.