
Bank of Canada Raises Its Rate to 2.5%: What It Means for Your Alberta Mortgage
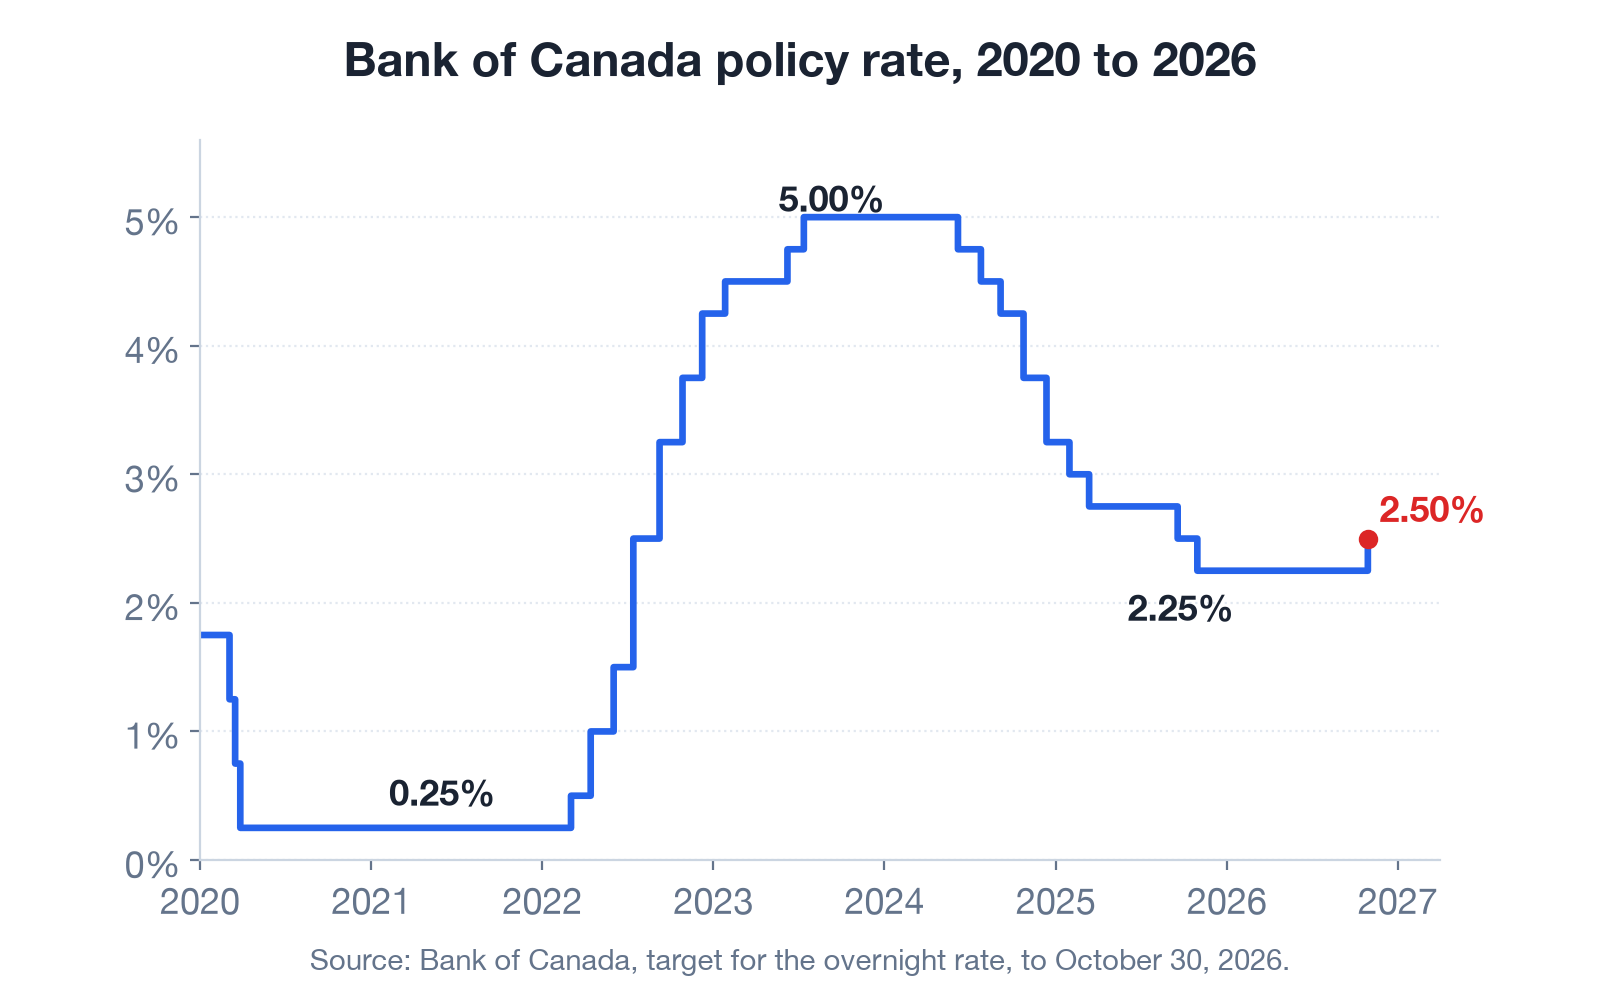
The Bank of Canada raised its policy rate from 2.25% to 2.50% on October 28, 2026, its first increase since July 2023 (Bank of Canada). The big banks moved their prime rates up the next day.
Three numbers matter most if you have a mortgage or plan to get one. The policy rate is 2.50%. Prime is 4.70% at Canada’s six largest banks (Canadian Mortgage Trends). And on November 2, the lowest advertised insured five-year rates in a lender survey were 3.50% variable and 4.39% fixed (lender rate survey, November 2, 2026). Those are the survey’s default rates on November 2, shown before you choose a province. They vary by province, can change within 24 hours and may include bought-down offers, so treat them as a snapshot of that day, not rates to expect. Ask us for a current quote. Our Alberta mortgage rates guide has the wider picture.
Key Takeaways
– The policy rate rose a quarter of a percentage point to 2.50%, and the next decision is December 9, 2026 (Bank of Canada).
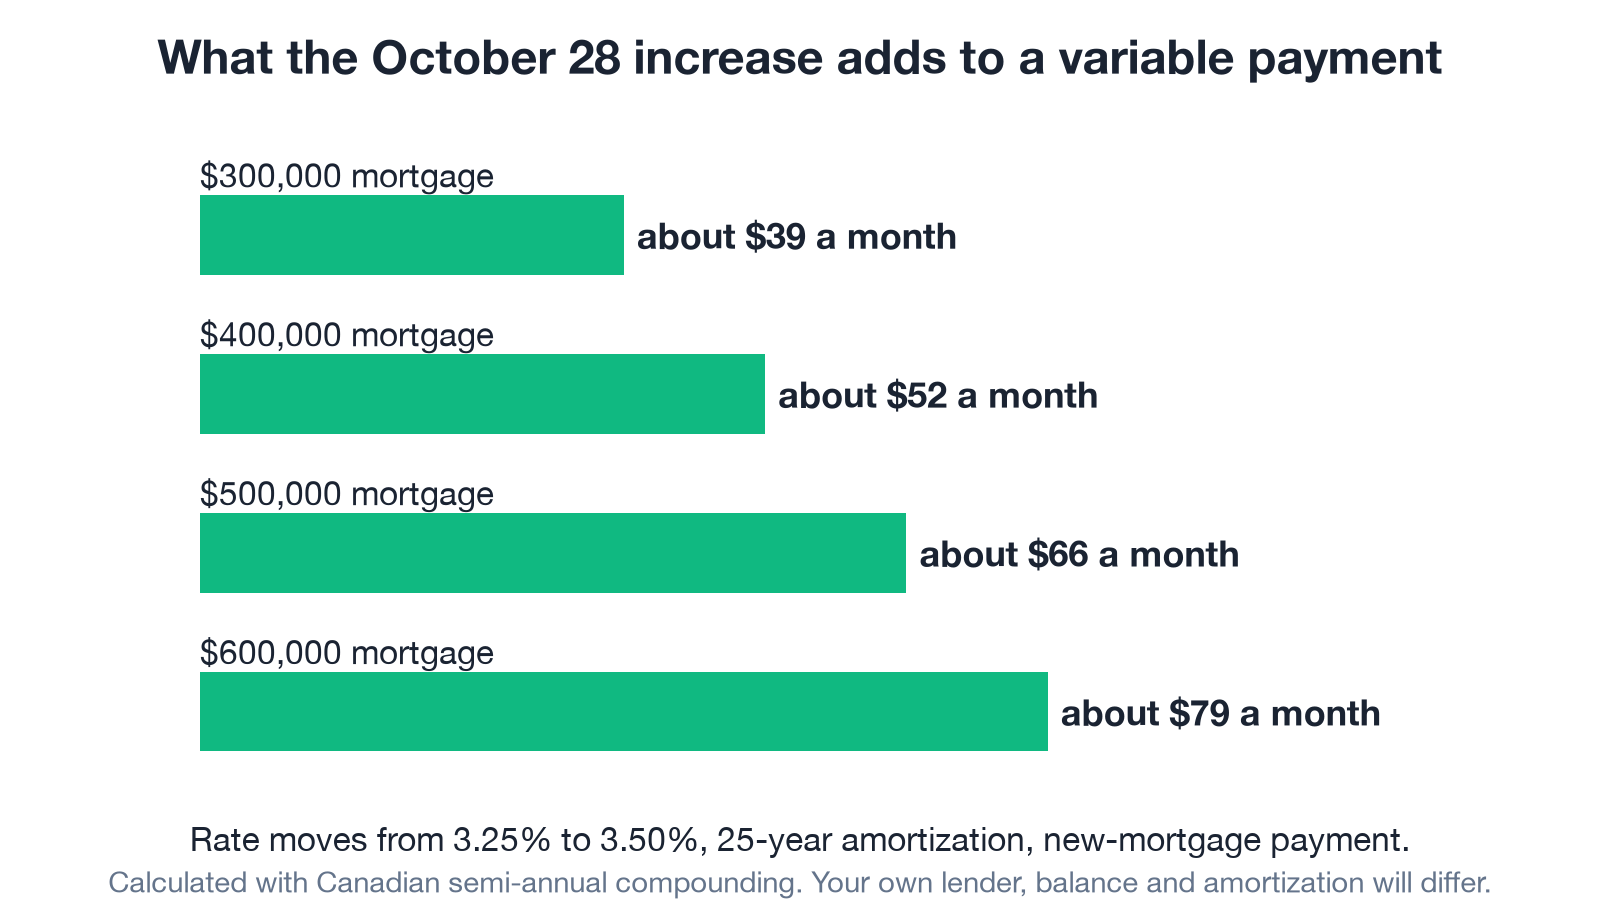
– Prime is now 4.70%. If your variable payment adjusts with prime, a quarter point adds about $66 a month on a new $500,000 mortgage.
– In a November 2 snapshot, the lowest advertised insured five-year fixed rate had risen to 4.39% even as the five-year bond yield fell (lender rate survey, November 2, 2026).
– In our example, a $450,000 mortgage signed in 2021 at 1.89% would renew about $467 a month higher at that day’s 4.39% five-year fixed rate.
What did the Bank of Canada decide on October 28?
The Bank raised its target for the overnight rate, known as the policy rate, by 25 basis points (a quarter of a percentage point) to 2.5%. The Bank Rate is now 2.75% and the deposit rate 2.45% (Bank of Canada). The policy rate had been 2.25% since late October 2025 (Bank of Canada).
Why did the Bank raise its rate?
The Bank wants to reduce the risk that continuing high energy prices spread broadly to other goods and services (Bank of Canada). CPI inflation has been around 3% since April, and the Bank expects it to reach about 3½% by the end of the year.
Excluding gasoline, inflation was only 2.2% in September, and measures of core inflation remain close to 2%. So why act now? The Bank now expects CPI inflation to average 3% in 2027, a percentage point above its July projection, before coming down to 2% in the middle of 2028.
Growth is the other half of the story. GDP rose 3.3% in the second quarter, recent indicators point to about 2% in the third, and the Bank says the growth outlook has improved modestly (Bank of Canada).
Two lines will sound familiar in Alberta. The Bank says business investment rebounded, reflecting oil and gas sector activity among other things. It also says high oil prices are “hitting Canadians at the gas pump” and raising costs for many businesses. It doesn’t name Alberta, but both land close to home here.
What changes if you have a variable-rate mortgage?
Your borrowing cost goes up. Prime rose a quarter of a percentage point to 4.70% at Canada’s six largest banks, effective October 29 (Canadian Mortgage Trends). RBC, for one, went from 4.45% to 4.70% (RBC). If you’re with TD, check its separate mortgage prime, which rose from 4.60% to 4.85%.
If your payment adjusts with prime
Your monthly payment goes up. Here’s what a quarter point adds on a new mortgage with a 25-year amortization, moving from 3.25% to 3.50%.
| Mortgage amount | Added to the monthly payment |
|---|---|
| $300,000 | About $39 |
| $400,000 | About $52 |
| $500,000 | About $66 |
| $600,000 | About $79 |
If you have a fixed payment
Your payment stays the same, but “more of each payment will go toward interest” (Canadian Mortgage Trends), so your balance falls more slowly. Our fixed vs. variable guide compares the two.
Did fixed rates go up too?
Yes, in the survey we checked. The lowest advertised insured five-year fixed rate was 4.39% that day, up 20 basis points in 30 days (lender rate survey, November 2, 2026). Fixed rates follow bond yields plus the margin each lender adds.
What’s unusual is that the five-year Government of Canada yield fell over roughly the same stretch, from 3.68% on September 28 to 3.51% on October 30 (Bank of Canada). A falling yield doesn’t guarantee a lower fixed quote.
Here’s where the survey’s default rates stood on November 2. They vary by province and can change within 24 hours, and some companies buy down the rates they advertise, so this is a snapshot of that day, not a quote.
| Mortgage | Lowest advertised rate, November 2 | Change over 30 days (basis points) |
|---|---|---|
| 1-year fixed, insured | 4.79% | +70 |
| 2-year fixed, insured | 4.54% | +45 |
| 3-year fixed, insured | 4.29% | +20 |
| 5-year fixed, insured | 4.39% | +20 |
| 5-year fixed, conventional | 4.44% | +20 |
| 5-year variable, insured | 3.50% | +25 |
| 5-year variable, conventional | 3.65% | +35 |
On $450,000 over 25 years, those lowest fixed and variable rates were about $216 a month apart. Our five-year fixed guide explains how fixed rates get set.
What should you do if your mortgage is coming up for renewal?
Compare lenders early and ask about a rate hold. The Financial Consumer Agency of Canada says that when you get preapproved you can lock in a rate for 60 to 130 days, depending on the lender (FCAC). You also don’t have to renew with the same lender (FCAC).
If you move an uninsured mortgage to another federally regulated lender with no increase to the loan amount or the amortization period, a straight switch, OSFI exempts it from the minimum qualifying rate, though the new lender still reviews your application like any other (OSFI). Our rate holds guide and mortgage renewal guide cover the steps.
A worked example: $450,000 at 1.89% from 2021
Take $450,000 signed in 2021 at 1.89% on a 25-year amortization. The payment is about $1,882 a month. After five years, about $376,100 remains, with 20 years to go.
| Renewal rate (November 2 snapshot, insured) | Monthly payment | Change |
|---|---|---|
| 4.39% five-year fixed | $2,349 | Up $467 (24.8%) |
| 3.50% five-year variable | $2,176 | Up $294 (15.7%) |
This is an illustration at that day’s rates, not a quote. An uninsured mortgage would start from that day’s conventional rates of 4.44% and 3.65%.
What does it mean if you’re buying in Edmonton or Calgary?
Your payment and your qualifying rate both go up with the rate you’re offered. Banks must use the higher of 5.25% or your contract rate plus 2% (FCAC). On that day’s lowest advertised rates, that made the test 6.39% fixed and 5.50% variable.
Here’s what those November 2 rates would mean on each market’s latest benchmark home, over 25 years. The minimum down payment is 5% of the first $500,000 of the price plus 10% of any portion above that (Financial Consumer Agency of Canada). Both homes fall in the band where the mortgage insurance premium is 4.00% of the loan (CMHC), and we’ve added it to the mortgage in the table.
| Greater Edmonton (September) | City of Calgary (October) | |
|---|---|---|
| Benchmark price | $423,100 | $564,200 |
| Minimum down payment | $21,155 | $31,420 |
| Mortgage, premium included | $418,023 | $554,091 |
| Payment at 4.39% fixed | $2,288 | $3,033 |
| Payment at 3.50% variable | $2,087 | $2,766 |
Greater Edmonton: September sales were 1,959, down 10.3% from a year earlier, while inventory rose 16.7% and the benchmark fell 0.3% (REALTORS® Association of Edmonton).
City of Calgary: October sales were 1,592, down 15.3% from a year earlier. Inventory fell 4.6%, the benchmark fell 0.4%, and months of supply came in at 3.88. CREB says the apartment and row sectors tend to favour the buyer, while detached and semi-detached markets remain relatively balanced (CREB).
Our Edmonton and Calgary rate pages work through payments at example rates.
Will the Bank raise rates again?
It might, and nobody can promise the outcome. “There could be a need to increase the policy rate further,” the Bank said, adding that Governing Council agreed to proceed carefully (Bank of Canada). Governor Tiff Macklem said decisions will come “one meeting at a time” (Bank of Canada).
Two parts of the Bank’s outlook pull in different directions:
- Toward another increase: CPI inflation is expected to reach about 3½% by the end of the year, and high oil prices are raising costs for many businesses.
- Toward holding back: New US tariffs are expected to slow growth in the fourth quarter of 2026, before it picks up again in 2027.
The next rate decision is December 9, 2026, and the next Monetary Policy Report comes January 27, 2027. If you’re deciding when to commit, our when-to-lock guide covers the timing, and our guide to buying or renewing after the rate hike has worked numbers for both.
How can Metro help you compare your options?
We compare 30+ lenders on your actual numbers. Pre-approval usually comes within 24 hours, and we hold a rate with one lender while we keep watching the market. Call 780-974-1270 or email info@MetroMortgageGroup.ca.
About the author: Daniel De Sousa is a co-owner of Metro Mortgage Group and leads its team of mortgage professionals. Metro has arranged mortgages for Alberta borrowers since 2010 and works with a network of 30+ lenders.
Sources
- Bank of Canada, Bank of Canada raises the policy rate by 25 basis points to 2½%, retrieved 2026-11-02, https://www.bankofcanada.ca/2026/10/fad-press-release-2026-10-28/
- Bank of Canada, Opening statement, October 28, 2026, retrieved 2026-11-02, https://www.bankofcanada.ca/2026/10/opening-statement-2026-10-28/
- Bank of Canada, Policy interest rate, retrieved 2026-11-02, https://www.bankofcanada.ca/core-functions/monetary-policy/key-interest-rate/
- Bank of Canada, Canadian bond yields, retrieved 2026-11-02, https://www.bankofcanada.ca/rates/interest-rates/canadian-bonds/
- Canadian Mortgage Trends, Big banks raise prime rates to 4.70% following BoC hike, retrieved 2026-11-02, https://www.canadianmortgagetrends.com/mortgage-wire/2026/10/28/big-banks-raise-prime-rates-to-4-70-following-boc-hike/
- RBC Royal Bank, RBC Royal Bank announces change to prime rate, retrieved 2026-11-02, https://www.newswire.ca/news-releases/rbc-royal-bank-announces-change-to-prime-rate-837555648.html
- Lender rate survey, lowest advertised Canadian mortgage rates, as of November 2, 2026, retrieved 2026-11-02, https://wowa.ca/mortgage-rates
- REALTORS® Association of Edmonton, New inventory is still being added, but sales have slowed for fall, retrieved 2026-11-02, https://realtorsofedmonton.com/statistic/new-inventory-is-still-being-added-but-sales-have-slowed-for-fall/
- CREB, City of Calgary Monthly Statistics, October 2026, retrieved 2026-11-02, https://www.creb.com/Housing_Statistics/documents/10_2026_Calgary_Monthly_Stats_Package.pdf
- Financial Consumer Agency of Canada, Down payment, retrieved 2026-11-02, https://www.canada.ca/en/financial-consumer-agency/services/mortgages/down-payment.html
- CMHC, Mortgage loan insurance premiums, retrieved 2026-11-02, https://www.cmhc-schl.gc.ca/consumers/home-buying/mortgage-loan-insurance-for-consumers/cmhc-mortgage-loan-insurance-cost
- Financial Consumer Agency of Canada, Preparing to get a mortgage, retrieved 2026-11-02, https://www.canada.ca/en/financial-consumer-agency/services/mortgages/preparing-mortgage.html
- Financial Consumer Agency of Canada, Getting preapproved for a mortgage, retrieved 2026-11-02, https://www.canada.ca/en/financial-consumer-agency/services/mortgages/preapproval-qualify-mortgage.html
- Financial Consumer Agency of Canada, Renewing your mortgage, retrieved 2026-11-02, https://www.canada.ca/en/financial-consumer-agency/services/mortgages/renew-mortgage.html
- Office of the Superintendent of Financial Institutions, OSFI exempts uninsured mortgage straight switches from the prescribed MQR, retrieved 2026-11-02, https://www.osfi-bsif.gc.ca/en/guidance/guidance-library/osfi-exempts-uninsured-mortgage-straight-switches-prescribed-mqr-implements-portfolio-lti-limits